“Excelente abogado y su equipo de trabajo recomendado … ganamos el caso gracias a Dios y al abogado”
Elsa RodríguezGoogle · ES
 Request a Case Review
Vehicle accidents
Car accidents Truck & 18-wheeler accidents Motorcycle accidents Drunk driver accidents
Hurt in an accident?
How much is my case worth?
Seven quick questions, then talk to an attorney.
Start the check
Homeowner insurance claims · McAllen, Texas
Tu casa importa
When a storm, hurricane or burst pipe damages your home, your insurance company has to follow Texas deadlines and pay what the policy covers. If your homeowner insurance claim was denied, delayed or underpaid, we review the policy and the adjuster's estimate, explain your options and deal with the insurer for you.
“Excelente abogado y su equipo de trabajo recomendado … ganamos el caso gracias a Dios y al abogado”
“100% recommend fought for my case until the end, always kept good communication and answered my questions …”
Insurance claim disputes
Your homeowner policy is a contract. You pay the premiums, and the company promises to pay for covered damage. A dispute starts when the company denies the claim, pays less than the repairs cost, or stops answering.
Texas sets deadlines for each step of a claim, and a company that owes a claim and pays late can owe interest and attorney's fees. Call us before you sign a release or let a deadline in your policy pass.
Why Alex Martinez Law
tu familia primero
Alex Martinez, licensed in Texas and admitted to the federal Southern District of Texas, represents insurance claim and injury clients across the Rio Grande Valley.
Adrian Martinez, of counsel, has more than 40 years of civil litigation and jury trial work, and practices alongside his son, Alex.
Meet us at our McAllen office or our Brownsville office in Olmito, or talk by phone, WhatsApp or video.
Call or WhatsApp us any time, and send photos of the damage straight from your phone.
You pay no attorney's fee unless we recover money for you.
How we handle your claim
Alex Martinez reads your policy and the insurer's letters first: what is covered, what was excluded and which deadlines are already running. Our team then requests the full claim file, gets an independent repair estimate when one is needed and keeps you updated by phone or WhatsApp.
Storm, water and payment disputes
Flood damage usually needs a separate flood policy. Most home policies don't cover floods, according to the Texas Department of Insurance home guide.
Roofs, windows and siding torn up by hurricanes and tropical storms.
Missing shingles, dented roofs, broken skylights and damaged fences.
Sudden leaks from plumbing, water heaters and appliances, and the damage they leave behind.
The company says the damage is excluded, too old or below your deductible.
The check does not cover what contractors say the repairs will cost.
Weeks of silence, repeated requests for the same papers or an adjuster who stopped calling.
General information, not legal advice. Exceptions apply. Texas Prompt Payment of Claims Act, Insurance Code chapter 542..
15 days
to acknowledge your claim, start the investigation and ask for what it needs.
15 business days
to accept or reject the claim in writing once it has what it asked for. It can take 45 more days if it tells you why.
5 business days
to pay after it accepts the claim, or after you do what the payment depends on.
61 days
Your notice before suing over storm or weather damage: in writing, with the amount owed.
Paying late costs the insurer. If it owes the claim and breaks these rules, it can owe interest plus attorney's fees. After a declared weather catastrophe, the deadlines stretch by 15 days. Ins. Code §542.058 to §542.060
Your deadline to sue. Your policy may set one, but Texas voids any contract deadline shorter than two years. Claims for unfair insurance practices also have a two-year limit. Civ. Prac. & Rem. Code §16.070; Ins. Code §541.162
Coastal wind and hail policies. Homes in Cameron County may have wind and hail coverage from the Texas Windstorm Insurance Association. Those claims must be filed within one year of the damage, with their own dispute steps. Ins. Code §2210.573, §2210.574
What happens next
Timing depends on the policy, the insurer and the court. These are typical stages, never a promise.
Send us the denial letter, the estimate or photos. An attorney reviews the policy and explains where the claim stands.
We get the full policy and claim file and, when needed, an independent estimate of the repairs.
We present the claim with the evidence. For weather claims, Texas requires written notice at least 61 days before a lawsuit.
If the dispute is only about the amount, the policy's appraisal clause may settle it. If coverage is denied, we negotiate.
If the insurer still will not pay, we can file suit before the deadlines in your policy and Texas law run out.
Fees and consultation
You pay no attorney’s fee unless we recover money for you.
Case costs, such as filing fees and records, are explained in writing before you sign.
Your claim review is free. Before you sign, we explain our fee and how case costs, such as repair estimates and court filing fees, are handled, and you get the agreement in writing.
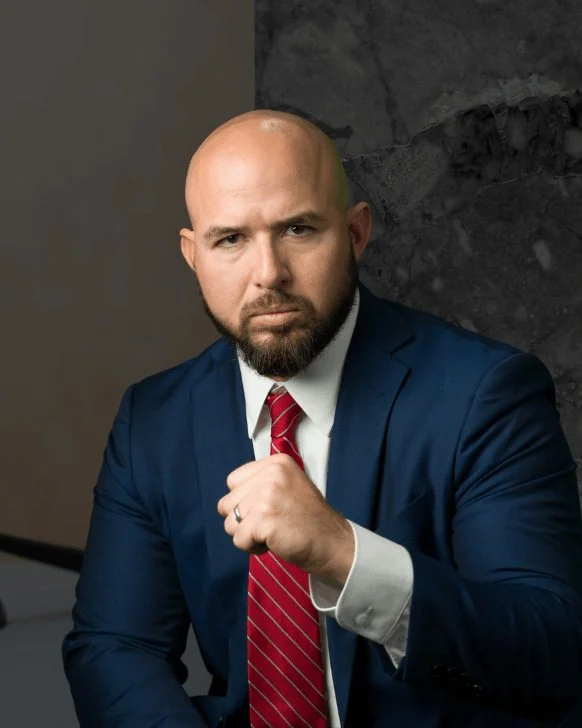
Your attorney
J.D., Thurgood Marshall School of Law. Licensed in Texas, admitted to the U.S. District Court for the Southern District of Texas. Works with Adrian Martinez, of counsel, a civil trial lawyer with more than 40 years in civil litigation.
Reviewed by Alex Martinez, State Bar of Texas
Questions
Sometimes. A denial is the insurer's position, and Texas requires it to give its reasons in writing. We compare those reasons with your policy and the damage. If they do not hold up, the claim can still be pursued with a demand, the policy's appraisal process or a lawsuit.
Usually five business days after it accepts the claim. Before that, it has 15 days to acknowledge the claim and 15 business days after it has everything it asked for to accept or reject it, with up to 45 more days if it explains why it needs them.
Appraisal is a process in many policies for disputes about the amount of the loss. You and the company each hire an appraiser, the two pick an umpire, and the result is binding on the amount. It does not decide whether the policy covers the damage, and you pay your own appraiser and half of the umpire, so we look at the numbers before recommending it.
It can help, and it is free. TDI's Help Line is 800-252-3439, and companies have 15 days to answer a complaint. TDI cannot make a company pay unless the refusal breaks a law or your policy, and it does not settle disputes about the facts, so a complaint is one step alongside your claim.
Usually not. Most Texas home policies don't cover flooding, which needs a separate flood policy. Water from a burst pipe or a storm-damaged roof is a different kind of claim, so the cause of the water matters.
Yes. Your policy may set one, but Texas does not allow a contract deadline shorter than two years. For storm and weather claims you must also send written notice at least 61 days before filing suit, so call well before any deadline.
Offices in McAllen and Brownsville. Phone and video consultations anywhere in the Valley.
Phone, WhatsApp or the form. English or Spanish, day or night.
Vehicle accidents
Car accidents Truck & 18-wheeler accidents Motorcycle accidents Drunk driver accidentsWorkplace
Workplace injuries Construction accidents Oilfield injuriesSerious injury & loss
Wrongful death Medical malpractice Sexual abuseSlip and fall & insurance
Slip and fall Homeowner insurance claims Immigration hubRemoval defense
Deportation defense Asylum Immigration bondsResidency
Green cards CitizenshipFamily
Family petitions DACA renewalsWork
Work permits & visas How much is my case worth? Check my USCIS case status USCIS processing times